Best Stocks and Shares ISA in 2026: What to Look For
Choosing the best Stocks and Shares ISA in 2026 is not just about finding the lowest headline fee. It is about finding the right combination of value, flexibility, investment choice, and ease of use.
A Stocks and Shares ISA allows you to invest in a tax-efficient wrapper, so any growth or income generated within the account is generally free from UK income tax and capital gains tax. For many investors, it remains one of the simplest and most effective ways to build long-term wealth. The ISA allowance is £20,000 for the 2025/26 tax year, and HMRC has confirmed the overall ISA subscription limit remains £20,000 into 2026/27 as well.
The challenge is that not all ISA providers are built the same. Some focus on simplicity, some focus on very low entry costs, and some are designed for investors who want more control, wider investment choice, and a more professional investment experience.
At Invinitive, we believe the best Stocks and Shares ISA is one that is clear on costs, easy to manage, and flexible enough to grow with you over time.
What is a Stocks and Shares ISA?
A Stocks and Shares ISA is an Individual Savings Account that lets you hold investments such as shares, funds, ETFs and other permitted investments in a tax-efficient wrapper.
Unlike a Cash ISA, the value of your investments can go down as well as up, so it is generally more suitable for people investing over the medium to long term rather than those who need certainty of capital.
For many people, a Stocks and Shares ISA works well if they:
- want the potential for better long-term returns than cash
- are comfortable investing for at least five years
- want to build wealth in a tax-efficient way
- value flexibility and access to a wide range of investments
Why Stocks and Shares ISAs remain important in 2026
The ISA remains one of the most valuable tax wrappers available to UK investors. The annual ISA allowance is £20,000, and that allowance can be used across your eligible ISA accounts each tax year. Since 6 April 2024, investors have also been able to subscribe to multiple ISAs of the same type in the same tax year, provided they stay within the overall allowance.
That means investors now have more flexibility than before. You may want one provider for cash savings and another for investing, or you may want to transfer to a provider that better suits your needs without giving up the tax benefits you have already built up.
What actually makes an ISA platform best?
There is no single best Stocks and Shares ISA for everyone. The right choice depends on your goals, portfolio size, and how hands-on you want to be.
1. Clear and fair charges
Charges matter, especially over the long term. Even small differences in fees can add up over many years. When comparing providers, look at the full picture rather than just one headline number. This may include:
- platform or custody fees
- dealing charges
- foreign exchange charges on overseas investments
- exit or transfer fees
- any additional service charges
A platform that looks cheap at first glance may become more expensive depending on how often you trade, whether you invest internationally, and how large your portfolio becomes.
2. Suitable investment choice
Some investors are happy with a small range of ready-made funds. Others want a wider choice of UK and international shares, ETFs, funds, and other permitted investments. The best ISA for you should give you access to the types of investments you actually want to hold.
3. A good user experience
A good ISA platform should be easy to understand and easy to use. You should be able to:
- view your holdings clearly
- understand your valuation
- place deals easily
- access documents and statements without hassle
- manage contributions and transfers smoothly
For long-term investors, simplicity and reliability often matter more than gimmicks.
4. Transfer flexibility
If you already have an ISA elsewhere, you may be able to transfer it to a new provider without losing its tax-efficient status. ISA transfers should always be completed using the formal transfer process. Withdrawing the money yourself and then reinvesting it can affect your allowance position unless the ISA is flexible and the replacement is made within the required rules.
5. Confidence and protection
It is important to choose a provider that is properly authorised and operates within the UK regulatory framework. FSCS protection may apply in certain circumstances, up to £85,000 per eligible person, per firm, depending on the type of claim and the regulated activity involved.
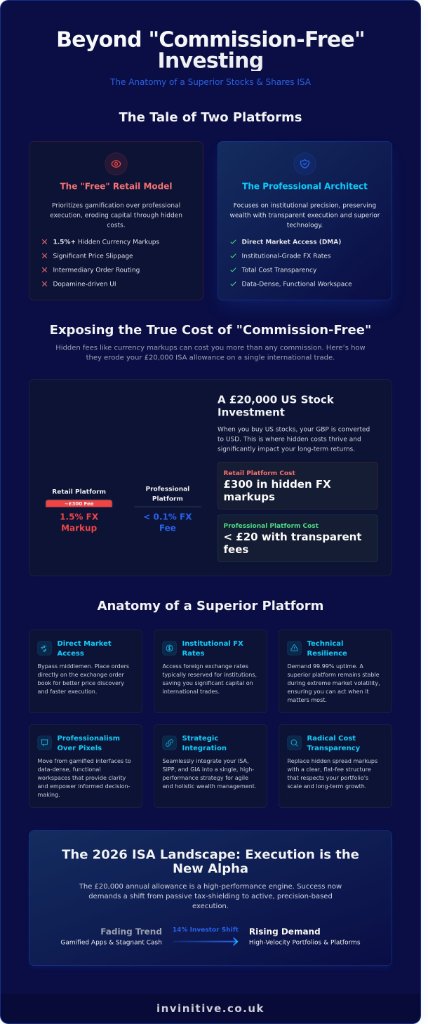
The hidden cost issue: look beyond free
One of the most common mistakes investors make is focusing only on whether a platform charges commission. In reality, the total cost of investing can include much more than a dealing fee. That is why it is worth asking:
- What will I actually pay in a typical year?
- How do the charges change as my account grows?
- Will I be investing in overseas shares or ETFs?
- Am I paying for features I do not need?
- Am I missing features that I will want later?
The cheapest-looking option is not always the best value.
How a Stocks and Shares ISA can fit with a SIPP and GIA
A Stocks and Shares ISA is often most effective when viewed as part of a wider savings and investment strategy.
- a Stocks and Shares ISA can provide tax-efficient investing with accessible withdrawals
- a SIPP can provide pension tax relief and long-term retirement planning
- a GIA can be useful once ISA and pension allowances have been used
Used together, these wrappers can help investors build a more flexible overall plan rather than relying on a single account type.
Why some investors choose Invinitive for their ISA
At Invinitive, our aim is to offer a Stocks and Shares ISA that is straightforward, cost-conscious, and suitable for investors who want control over their money without unnecessary complexity. Clients often value:
- a clean digital experience
- access to a broad investment range
- transparent charging
- the ability to hold investments as part of a wider strategy alongside SIPPs and GIAs
- support from a UK regulated business
Is a Stocks and Shares ISA right for you?
A Stocks and Shares ISA could be suitable if you:
- want to invest for the medium to long term
- understand that investments can fall as well as rise
- want to make the most of your annual ISA allowance
- are looking for tax-efficient growth and income
- want more flexibility and choice than a basic savings product offers
It may be less suitable if you need guaranteed returns, easy access to all of your money in the short term, or you are uncomfortable with investment risk.
Final thoughts
The best Stocks and Shares ISA in 2026 is not necessarily the one with the loudest marketing or the lowest advertised dealing fee. It is the one that fits your needs, keeps costs clear, offers the right investment choice, and gives you confidence to invest for the long term.
Frequently Asked Questions
What is the ISA allowance for 2025/26 and 2026/27?
The overall ISA allowance is £20,000 for the 2025/26 tax year, and HMRC has confirmed it remains £20,000 for 2026/27.
Can I pay into more than one Stocks and Shares ISA in the same tax year?
Yes. Since 6 April 2024, you can subscribe to multiple ISAs of the same type in the same tax year, as long as you stay within the overall ISA allowance.
Can I transfer an existing ISA?
In many cases, yes. You should use the official ISA transfer process so that your money keeps its tax-efficient status.
Is my money protected?
FSCS protection may apply up to £85,000 per eligible person, per firm, depending on the nature of the claim and the regulated activity involved.
Is a Stocks and Shares ISA better than a Cash ISA?
That depends on your goals and timescale. A Cash ISA may suit short-term saving and lower risk tolerance, while a Stocks and Shares ISA is generally more appropriate for long-term investing where you are comfortable taking investment risk.
Do I need a financial adviser to open a Stocks and Shares ISA?
Not always. Some investors are comfortable making their own decisions, while others prefer advice. The right route depends on your confidence, experience, and the complexity of your circumstances.
Looking for a flexible Stocks and Shares ISA?
Explore the Invinitive Stocks and Shares ISA and see how it can fit alongside your wider investment strategy.
Important Information
Important information: The value of investments can go down as well as up, and you may get back less than you invest. Tax rules depend on individual circumstances and may change in future. This guide is for general information only and does not constitute personal financial advice or a recommendation.